Finsamudra Newsroom, home

Finsamudra Desk

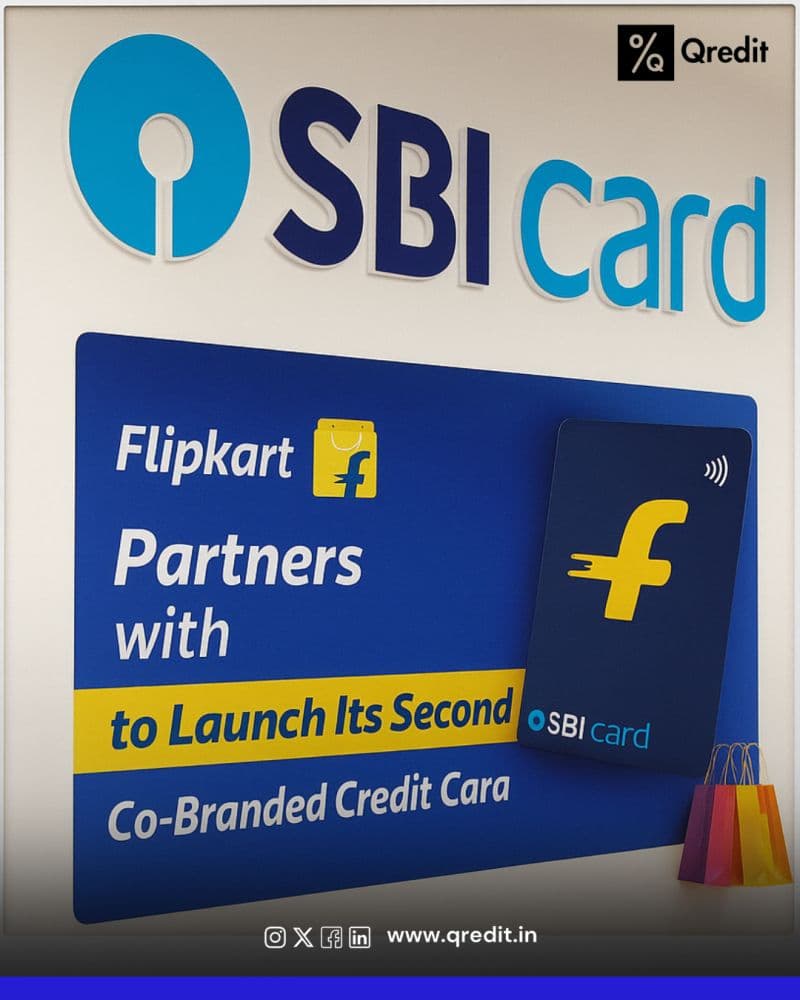
SBI Card launches Flipkart co-brand with 7.5% cashback on Myntra, 5% on e-commerce

The August 2025 card targets digital-first shoppers with tiered cashback across e-commerce, food, and travel. Annual fee of ₹500 is waived on spends above ₹3.5 lakh.

7.5% on MyntraHighest cashback tier
#️⃣ SBI Card x Flipkart: A New Cashback Powerhouse for Digital Shoppers,
Image: Finsamudra LinkedIn archive
₹3.5 lakh+ spendsAnnual fee waiver threshold
August 2025Card launch month

SBI Card and Flipkart have introduced a co-branded credit card designed for India's growing pool of online shoppers. The card launches with a tiered cashback structure: 7.5% on Myntra (capped at ₹4,000 per quarter), 5% on Flipkart, Shopsy, and Cleartrip, and 4% on partner merchants including Zomato, Uber, Netmeds, and PVR. Cardholders earn 1% unlimited cashback on all other eligible spends.

New cardholders receive a ₹250 Flipkart e-gift card as joining bonus, with additional festive-season contests tied to the Big Billion Days and Diwali shopping cycles. The card carries a ₹500 annual fee, but this is waived if annual spends exceed ₹3.5 lakh—a threshold designed to appeal to frequent online shoppers.
Beyond cashback, the card bundles lifestyle features: fuel surcharge waiver, contactless payment, global ATM access, and Flexipay EMI options. These additions position the card as a comprehensive payment tool rather than a rewards-only product, addressing the diverse financial needs of digital-first consumers.

The card's design reflects a clear trend: co-branded partnerships between fintech-enabled banks and e-commerce platforms are deepening customer engagement ahead of peak shopping seasons. For SBI Card, the partnership taps into Flipkart's user base of value-conscious, digitally native shoppers. For Flipkart, it locks in payment rails and increases wallet share.

Why it matters

For DSAs and lending connectors, co-branded cards represent a high-margin product attach opportunity. By bundling credit offers with e-commerce platforms, banks can reach borrowers at point-of-purchase, reducing acquisition friction. The cashback mechanics also signal how issuers are using rewards to subsidise customer acquisition and increase card spends—a shift that impacts the economics of credit distribution partnerships.

For lenders and banks, this card competes directly in the high-spend, low-risk segment: digital-first millennials and Gen Z with proven online transaction histories. The waiver threshold of ₹3.5 lakh annual spends identifies a cohort likely to generate consistent transaction volumes and higher interchange revenue. As festive shopping peaks, such cards become critical acquisition tools in a crowded market.

More on SBI

Every story on SBI →

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 4 Sept 2025, 12:14 am IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.