Finsamudra Newsroom, home

Finsamudra Desk

RBI set to restart urban co-op bank licenses after 22-year freeze

The central bank has proposed reopening the door to new urban co-operative bank licenses, halted since 2001, with strict capital requirements to prevent repeat failures.

₹300 croreMinimum capital requirement for applicants
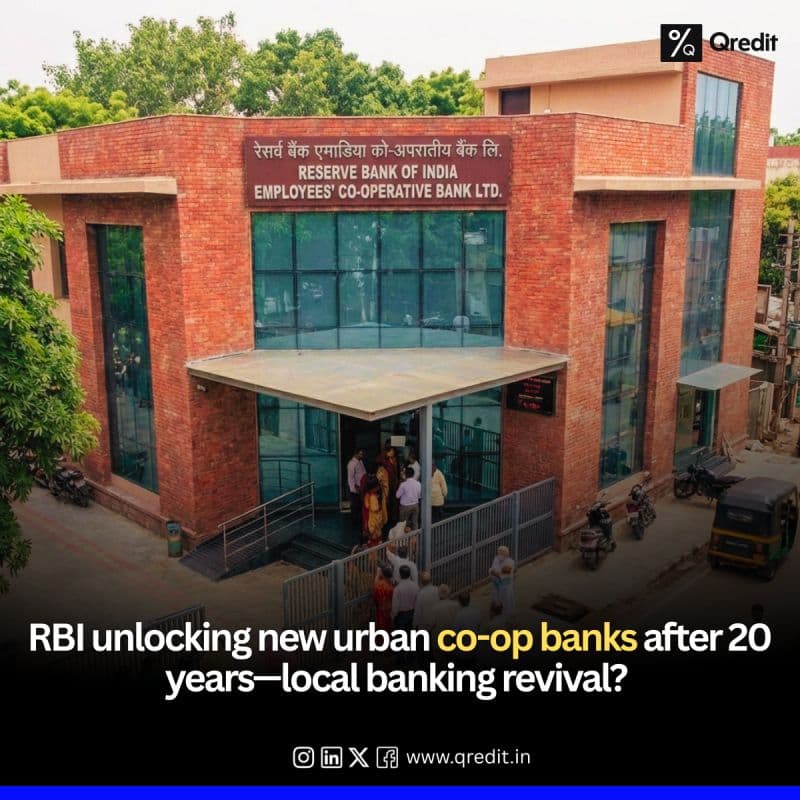
RBI greenlight for new urban co-op banks after 20+ years? Game changer! 🏦economictimes.indiatimes
Image: Finsamudra LinkedIn archive
22+ (freeze began 2001)Years since last urban co-op bank license

The Reserve Bank of India has signalled a shift in policy on urban co-operative banks, indicating plans to resume issuing new licenses after more than two decades. The RBI had stopped granting licenses in 2001 following a series of failures in the sector that eroded confidence among depositors and regulators.

The proposed framework comes with stringent guardrails. New applicants would need to demonstrate financial strength and governance capabilities, with the RBI suggesting a minimum capital requirement of ₹300 crore for established, well-governed societies seeking to convert or launch as banks.

This move acknowledges that the urban co-op sector has matured since the early 2000s. Prospective operators would face enhanced regulatory scrutiny and compliance standards, addressing the operational and management weaknesses that triggered the 2001 freeze.

The RBI's proposal is still under consultation and has not yet been formalized into final regulation. The central bank is seeking feedback on the framework from stakeholders, including existing co-operative societies, state governments, and the financial services industry.

Why it matters

For DSAs and loan connectors, fresh urban co-op bank licenses could expand the lender base available to source through—particularly in underserved localities and semi-urban pockets where co-ops historically have deep community roots. More licensed banks in the ecosystem means more distribution partners and potential volume growth channels.

From a borrower and credit access angle, localized co-operative banks can move faster on small-ticket lending to retail and MSME segments, reducing the friction and documentation burden that often characterizes larger institutional lenders. For neighbourhoods lacking adequate formal credit infrastructure, this revival may meaningfully ease access to working capital and term finance.

More on the RBI

Every story on the RBI →

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 14 Jan 2026, 2:00 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.