Finsamudra Newsroom, home

Finsamudra Desk

Urban inflation outpaces salary growth 2.4x; education costs surge nearly 4x

Indian salaries have doubled since 2016, but housing, fuel, and schooling have climbed faster, squeezing middle-class discretionary income and forcing a rethink of savings strategy.

₹6,790 → ₹25,000Education Costs
If you look at the data from the last decade, India’s average monthly salary has more than doubled. On paper, we are getting richer. But when you look at the actual cost of living
Image: Finsamudra LinkedIn archive
₹27,800 → ₹67,000Average Monthly Salary
₹65 Lakh → ₹1.17 CroreAverage House Price

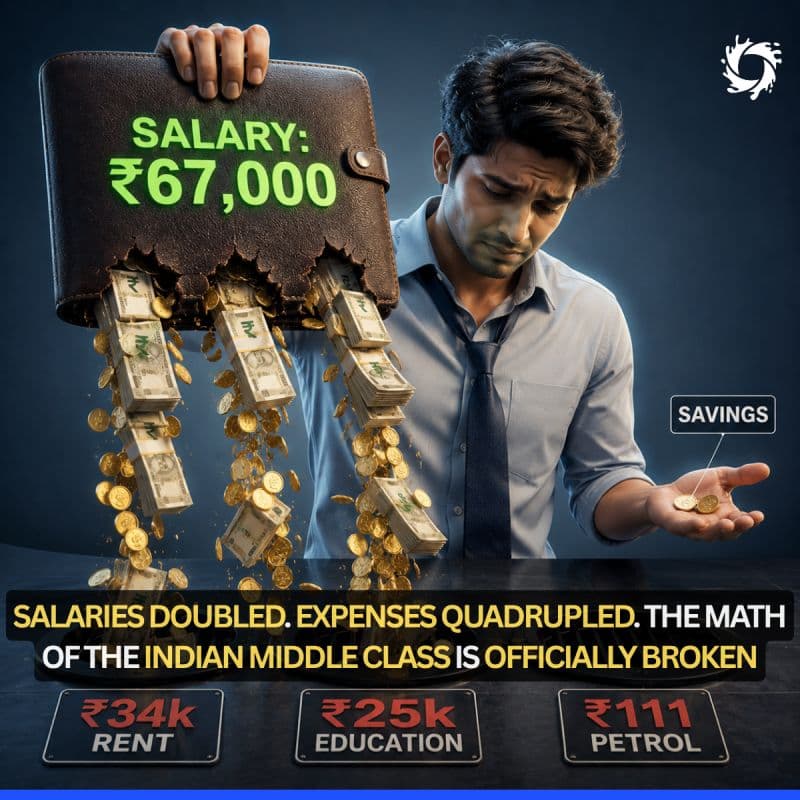
India's average monthly salary has climbed from ₹27,800 in 2016 to ₹67,000 in 2026—a 2.4x jump. Yet headline income growth masks a troubling divergence: the cost of essential expenses has risen faster, eroding real purchasing power for urban families.

Housing pressures lead the squeeze. Average house prices have risen 1.8x (₹65 lakh to ₹1.17 crore), while 2BHK urban rents have climbed 1.8x (₹19,000 to ₹34,000 monthly). For renters and buyers alike, shelter now claims a larger share of disposable income than a decade ago.

Fuel and education have proven even more punishing. Petrol prices are up 1.7x (₹65/L to ₹111/L), while education costs have nearly quadrupled (₹6,790 to ₹25,000)—a shock to household budgets with school-age children.

The cumulative effect is structural, not cyclical. Middle-class families are funnelling significantly larger percentages of their income toward non-negotiable survival costs, leaving proportionally less for wealth-building, investments, and retirement savings. This is not lifestyle inflation; it is a shrinking margin for financial optionality.

Why it matters

For lenders and DSAs, this reality reshapes credit demand and repayment capacity. Borrowers may report higher nominal incomes but face squeezed cash flow after essentials. Loan ticket sizes, tenure, and risk assessment must account for this structural inflation gap—traditional affordability ratios no longer reflect true household discretionary capacity.

Fintech connectors targeting middle-income segments need to pivot. Products anchored on historical savings patterns or income multiples will miss the mark. As traditional savings accounts fail to protect purchasing power, demand for higher-return investment products and flexible credit solutions will intensify, but only among borrowers with genuine breathing room after inflation-driven fixed costs.

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 2 Jun 2026, 2:30 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.