Finsamudra Newsroom, home

Finsamudra Desk

Muthoot Microfin shifts to 70:30 secured lending mix to de-risk portfolio

The MFI is pursuing a Loan Against Property company to balance high-yield micro-credit with collateralized assets, targeting semi-urban borrowers who have outgrown small loans.

70%Target unsecured loans
Muthoot Microfin’s pursuit of a Loan Against Property (LAP) company isn't just a business expansion—it’s a calculated shift in the Indian lending narrative.
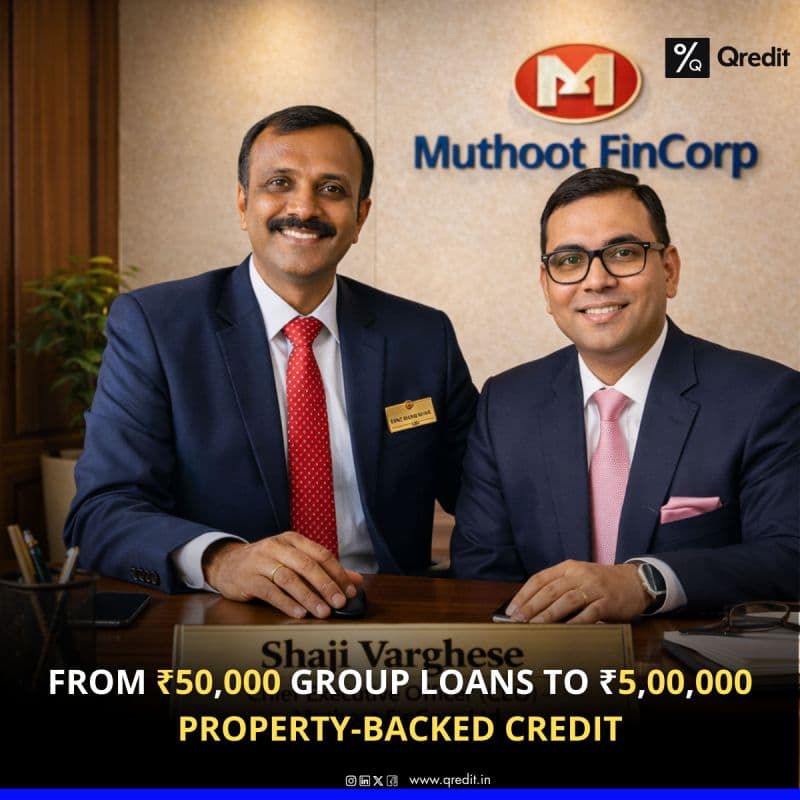
Image: Finsamudra LinkedIn archive
30%Target secured loans
₹5 lakh+Minimum loan size for graduated borrowers

Muthoot Microfin is reshaping its credit strategy under CEO Sadaf Sayeed, moving away from the traditional group-liability model that has defined microfinance in India. The company is now targeting a 70:30 split favouring unsecured over secured loans—a calculated rebalancing of its portfolio rather than an overhaul.

The push into Loan Against Property (LAP) serves three strategic purposes: de-risking the portfolio by mixing high-yield micro-credit with stability of collateralized assets; capturing the "graduated" borrower who needs ₹5L+ for business expansion but has outgrown ₹50k loans; and extending tenure to insulate the balance sheet from the typical 2-year micro-credit volatility.

This expansion sits within a broader vision from the Muthoot Pappachan Group. CEO Shaji Varghese at Muthoot FinCorp is orchestrating a three-pronged strategy across the holding company's lending arms, creating a pathway for borrowers to graduate from starter-kit loans to fully-collateralized property loans.

The shift reflects a deeper narrative change in Indian lending. MFIs have traditionally thrived on unsecured, group-backed credit to semi-urban and rural borrowers. But as borrower segments mature and seek larger ticket sizes, the business case for secured lending becomes unavoidable.

By 2026, according to the LinkedIn post's framing, the winners will be lenders who can transition borrowers across loan types—not those who lend fastest. This suggests Muthoot is betting on customer lifecycle monetization over volume-first metrics.

Why it matters

For DSAs and connectors, this signals a shift in the credit ecosystem. Borrowers who have performed well on micro-loans will now be eligible for larger secured facilities, creating upsell opportunities in your pipeline. But it also means the days of pure unsecured, high-volume micro-credit may be numbered—expect pressure to move upmarket.

For lenders and NBFCs, Muthoot's move underscores a structural challenge: high-velocity unsecured micro-lending faces duration and volatility constraints. Secured lending—despite lower yields—offers the tenure and stability needed to build sustainable portfolios. Any NBFC still betting solely on unsecured small loans will face margin pressure as competition for quality borrowers intensifies.

More on Muthoot

Every story on Muthoot →

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 18 Feb 2026, 1:00 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.