Finsamudra Newsroom, home

Finsamudra Desk

Three legacy cores dominate Indian banking, but AI agility will determine winners

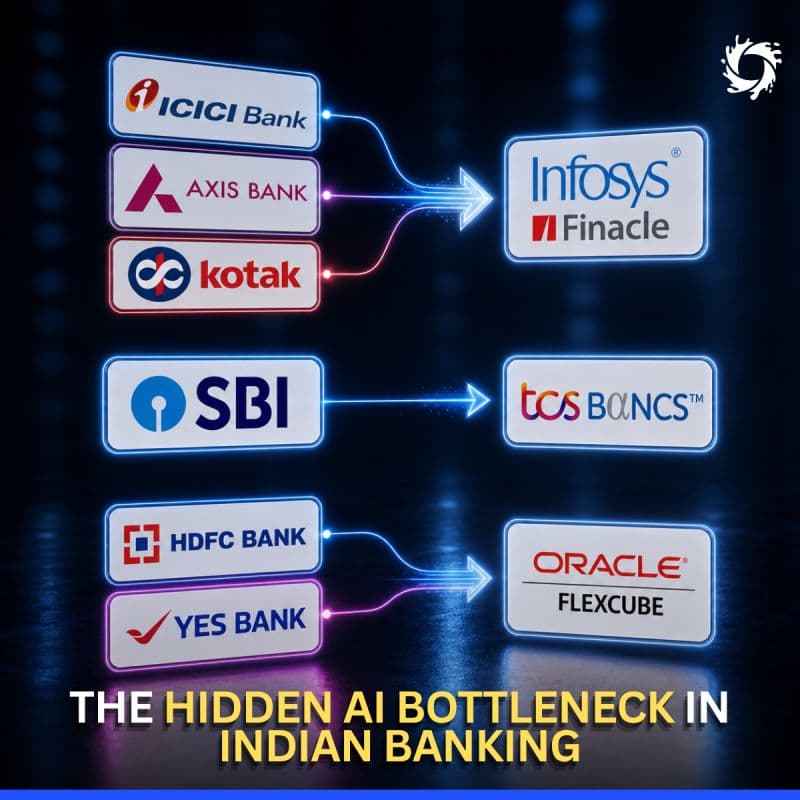
India's banks run on just three Core Banking Systems. Vendor consolidation enabled historic digitization—but now constrains innovation speed as the industry pivots toward AI-native architectures.

↳Look at India's banking ecosystem, and you will notice a massive structural concentration: almost every major public and private bank runs on just three Core Banking Systems (Info
Image: Finsamudra LinkedIn archive

India's major public and private banks operate on one of three Core Banking Systems: Infosys Finacle, TCS BaNCS, or Oracle Flexcube. This structural concentration was a feature, not a flaw—it allowed the Indian banking ecosystem to digitize at scale over two decades. But that same consolidation now presents a strategic liability as banks compete on speed and intelligence.

When an entire industry relies on the same legacy architectures and integration models, innovation speed is capped by the slowest component. Banks cannot move faster than the monolithic core allows. Product launches, data flows, and risk controls all bottleneck at legacy layers never designed for real-time AI workloads.

The strategic conversation has shifted. Banks are no longer debating core banking replacement—a multi-year, liability-laden undertaking. Instead, forward-thinking institutions are building composable, AI-native architectures around their existing cores, using API-first integration, event-driven microservices, and modular capability stacks.

The mandate for banking CIOs has fundamentally changed. General digital transformation is table stakes. The real challenge is deploying AI safely at scale in heavily regulated environments with minimal operational friction. Banks that master this will move faster to market with new products and real-time data intelligence.

Over the next decade, market share will not correlate with balance sheet size. It will correlate with architectural inertia—or lack thereof. The banks with the lowest friction to deploy innovation, not the largest deposit bases, will capture growth in India's credit distribution ecosystem.

Why it matters

For DSAs and loan agents, this architectural transition directly impacts speed to market and product agility. Banks hamstrung by legacy cores move slowly on new lending products, underwriting models, and compliance frameworks. DSAs working with banks that successfully modernize their stacks will access fresher products, faster policy updates, and better real-time data integration—all of which improve connector economics and borrower experience.

For lenders and NBFCs, the implication is clear: legacy-first banks will struggle to compete on product innovation and risk pricing. Those who decouple AI and data workloads from their monolithic cores—using composable architectures—will outmaneuver slower competitors. In lending, speed to deploy better underwriting, faster approvals, and dynamic pricing is now a survival metric.

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 2 Jun 2026, 12:15 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.