Finsamudra Newsroom, home

Finsamudra Desk

ESAF Small Finance Bank crosses ₹50,000 Cr business, eyes repeat in half the time

The Kerala-based lender's MARG strategy has pushed secured assets past 60% of its loan book, marking a deliberate pivot away from microfinance.

₹50,000 CrTotal business milestone
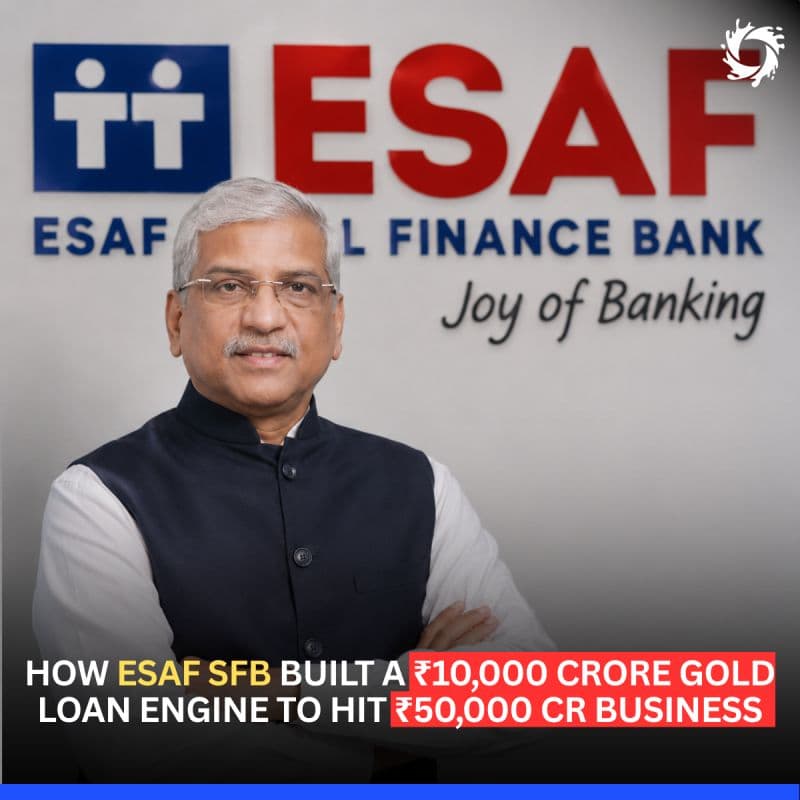
It took ESAF SMALL FINANCE BANK LTD nine years to reach its first ₹50,000 crore in total business. Their CEO expects the next ₹50,000 crore to come in half that time.
Image: Finsamudra LinkedIn archive
₹10,000 Cr+Gold loans
90%+ of ₹26,000 Cr total depositsRetail deposits share

ESAF Small Finance Bank Ltd, led by MD & CEO Dr. K Paul Thomas, has crossed ₹50,000 crore in total business — a milestone that took nine years to reach. The CEO expects the bank's next ₹50,000 crore to take half that time.

The growth is anchored in ESAF's MARG strategy: MSME Loans, Agri Financing, Retail Credit, and Gold Loans. This four-pronged approach has driven a shift away from uncollateralized microfinance toward secured lending.

Secured MARG assets now make up over 60% of ESAF's total loan book. Gold loans alone have crossed ₹10,000 crore, becoming a significant contributor to the bank's asset mix.

On the liability side, ESAF holds ₹26,000 crore in total deposits, with over 90% coming from retail deposits — a sign of disciplined, granular liability management.

The bank's roadmap includes capping unsecured micro-lending at 30%, launching FCNR(B) dollar products targeted at South-East Asian and Gulf NRIs, diluting promoter equity to 26% by 2031, and preparing its balance sheet for a Universal Bank license.

Why it matters

For DSAs and connectors working with small finance banks, ESAF's pivot signals where origination volumes are headed: gold loans, agri financing, and secured retail credit, rather than unsecured microfinance. Distribution partners aligned with these product lines stand to benefit as ESAF scales its book.

The MARG strategy also offers a template for other SFBs under stress in unsecured lending — showing that a disciplined shift toward secured assets and retail deposits can support both balance sheet growth and a credible path toward a Universal Bank license, which would open up broader lending mandates for connectors in the ecosystem.

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 25 Jul 2026, 1:45 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.