Finsamudra Newsroom, home

Finsamudra Desk

How Aditya Puri built HDFC Bank on discipline, not FOMO

By refusing the 2004-2007 infrastructure lending boom that other Indian banks chased, HDFC Bank kept gross NPAs at 0.85% while the industry average hit 6%.

0.85% vs 6%Gross NPAs: HDFC Bank vs industry average
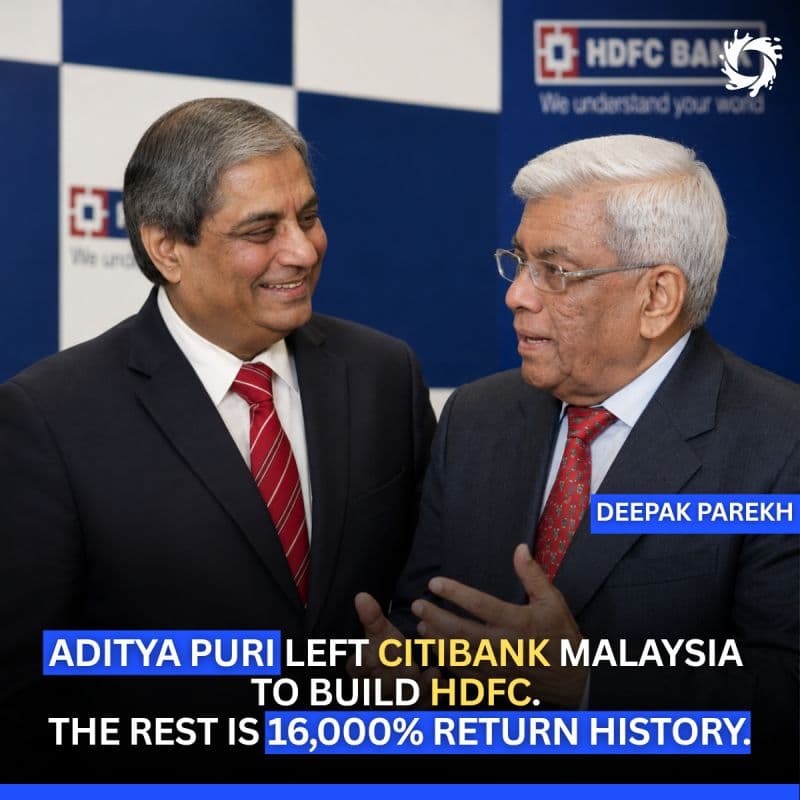
In 1994, the CEO of Citi Malaysia got a call from India. Deepak Parekh had a simple offer: return home and build HDFC Bank from scratch. The catch? The salary was less than half of
Image: Finsamudra LinkedIn archive
20% for over two decadesAnnual net profit compounding
16,000%Shareholder return over 25 years

In 1994, Deepak Parekh asked Aditya Puri, then CEO of Citi Malaysia, to return to India and build HDFC Bank from scratch. Puri took the role for less than half his Citi salary and ran the bank for the next 26 years.

The defining test came during the 2004-2007 credit boom, when Indian banks aggressively wrote large loans to infrastructure projects. It was profitable in the short term and every major competitor chased the business. Puri declined, holding to a rule that a short-term opportunity is not worth taking if it compromises the long-term plan.

While rival banks spent the following decade working through corporate NPAs, HDFC Bank spent that decade scaling low-risk retail consumer loans instead.

The results: gross NPAs held at 0.85% against an industry average of 6%. Net profits compounded at 20% a year for over two decades, and HDFC Bank became the 10th most valuable bank in the world by 2020.

The Economist later ranked Puri's performance against CEOs of the world's top 50 banks and placed him first. Shareholders saw a 16,000% return over 25 years, ahead of global banks like J.P. Morgan and HSBC.

Why it matters

For lenders and DSAs, the lesson is about portfolio discipline over cycle-chasing: HDFC Bank's refusal to write infrastructure loans during a boom that peers found irresistible is what kept its NPA book clean a decade later. In India's credit distribution business, the loans a lender or connector turns down during a hot cycle often matter as much as the ones they book.

For connectors and DSAs sourcing loans today, the takeaway is that retail, low-risk consumer credit — the segment HDFC quietly scaled while rivals chased infrastructure lending — proved to be the more durable growth engine over a 20-year compounding period. Sourcing quality and asset selection, not just volume, is what determines which side of the NPA gap a lender ends up on.

More on HDFC Bank

Every story on HDFC Bank →

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 15 Jul 2026, 2:00 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.