Finsamudra Newsroom, home

Finsamudra Desk

Kotak Mahindra Bank targets ₹3 spot via NBFC acquisitions, sitting on 23% capital adequacy

CEO Ashok Vaswani signals aggressive M&A strategy to deploy excess capital and scale the bank rapidly. The move hints at consolidation pressure across Indian financial services.

Nearly 23%Capital Adequacy Ratio
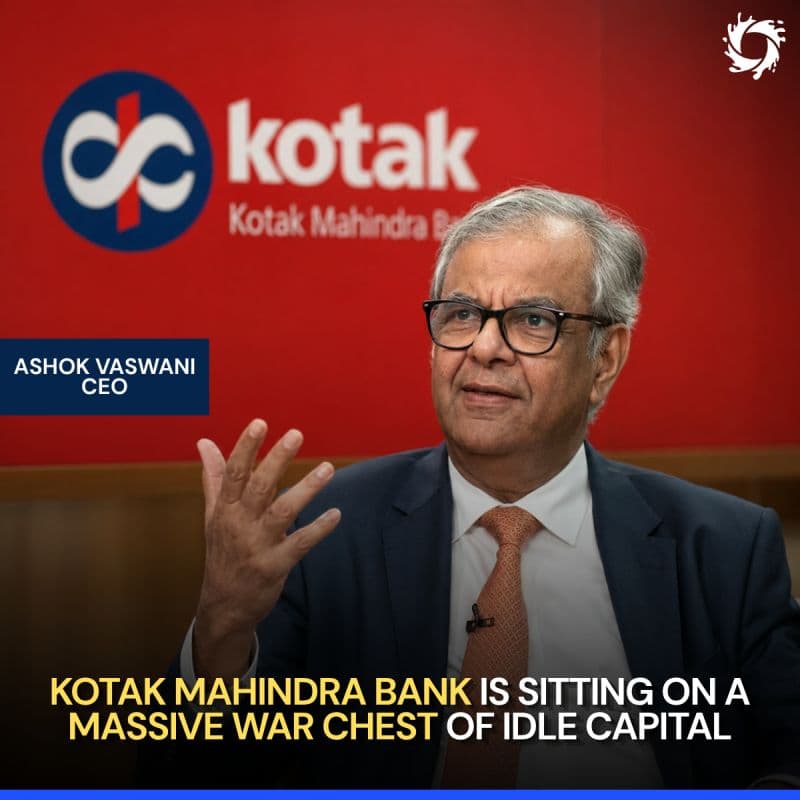
➤For years, Kotak Mahindra Bank has operated with a famously conservative balance sheet. Today, they are sitting on a staggering Capital Adequacy Ratio (CAR) of nearly 23%—massivel
Image: Finsamudra LinkedIn archive
#3 spot by after-tax profit among India's private lendersStrategic Goal

Kotak Mahindra Bank has long prided itself on conservative balance-sheet management. Today, that caution has translated into a Capital Adequacy Ratio (CAR) of nearly 23%—well above regulatory requirements. While safety is valuable, holding excess capital suppresses Return on Equity (RoE) and creates pressure to deploy funds productively.

The strategy has shifted. CEO Ashok Vaswani has publicly declared that Kotak now has 'high ambitions' to aggressively deploy this excess capital, moving beyond slow organic branch expansion. The bank is actively hunting for Mergers & Acquisitions opportunities.

Specifically, Kotak is evaluating targets to acquire massive loan portfolios and entire Non-Banking Financial Companies (NBFCs). This represents a sharp departure from the bank's historical playbook and signals intent to move fast.

The ultimate goal is clear: rapidly scale and permanently propel Kotak into the number 3 spot among India's private sector lenders by after-tax profit. This is no longer a distant aspiration but an officially declared mandate.

When a historically conservative giant with ₹23% CAR starts hunting for major acquisitions, it often signals the beginning of a consolidation wave across Indian financial services. Other players will likely respond.

Why it matters

For DSAs and loan connectors, Kotak's acquisition spree has direct implications. Large NBFC acquisitions will reshape the credit distribution landscape—new entrants, merged entities, and shifting scoring and approval criteria. Connectors tied to target NBFCs may see portfolio acquisition, repricing, or integration into Kotak's systems. DSAs should monitor which entities Kotak acquires and adjust partnerships accordingly.

For lenders and loan agents more broadly, this consolidation signals tightening competition at scale. A stronger, capital-deployed Kotak will compete harder for market share, likely pushing pricing pressure and stricter underwriting. Smaller lenders and independent DSAs will need to defend niches or form alliances. The hunt for efficiency and cost synergies post-acquisition will ripple through the entire distribution network.

More on Kotak

Every story on Kotak →

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 23 Jun 2026, 4:15 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.