Finsamudra Newsroom, home

Finsamudra Desk

Karur Vysya Bank pivots to growth after decade of balance-sheet cleanup

The mid-sized private lender is expanding into corporate lending, affordable housing, credit cards, and microfinance partnerships to lift yields after years of de-risking.

🔸 For the past decade, Karur Vysya Bank(KVB) worked diligently on a major consolidation act—de-risking its balance sheet, pruning wholesale exposure, and building asset quality.
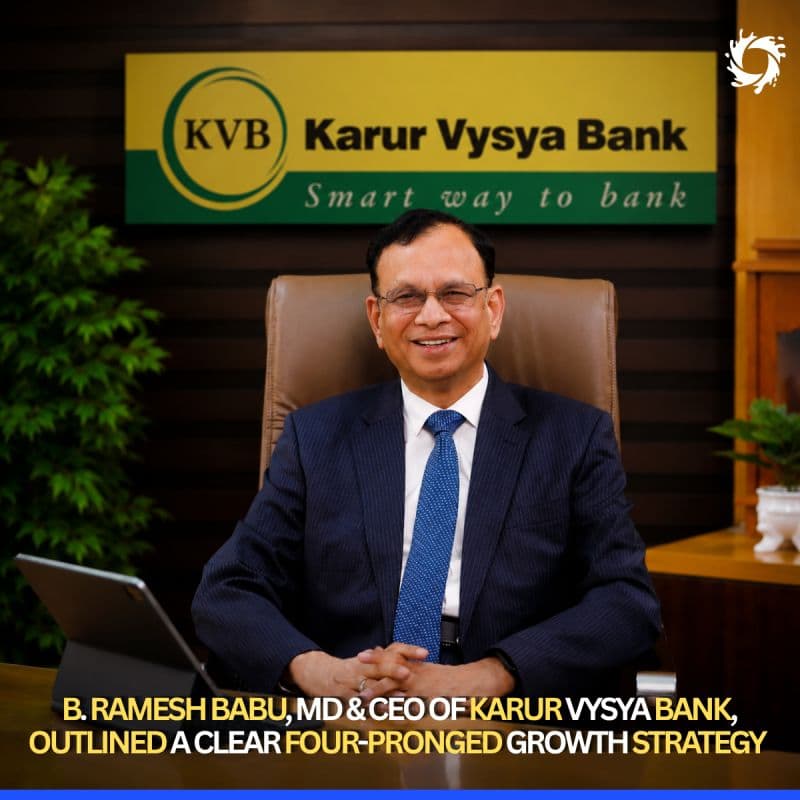
Image: Finsamudra LinkedIn archive
14% → 20% of loan bookCorporate lending target (2-year horizon)
₹20 lakh to ₹50 lakhAffordable housing ticket range

Karur Vysya Bank has spent the past decade pruning its wholesale exposure and repairing asset quality. Under MD & CEO B. Ramesh Babu, the lender is now shifting strategy: it plans to scale corporate loans from 14% to 20% of its loan book over two years, marking a deliberate re-entry into a segment it had intentionally downsized to clean up NPAs.

The bank's growth push extends across four channels. It is targeting the affordable housing segment (₹20 lakh to ₹50 lakh ticket range) to improve yields, launching an in-house credit card business to capture high-margin retail spend and cross-sell to depositors, and scaling microloans through co-lending partnerships and business correspondents.

New niche retail products—loans against mutual funds are among them—sit alongside the microfinance push. Together, these moves reflect a calculus: yield expansion without reckless risk-taking. The strategy signals confidence that KVB's balance sheet is now clean enough to absorb higher-risk, higher-return segments.

Mid-sized private banks are no longer content to operate as regional deposit havens. By rebuilding corporate books with strict risk discipline while diversifying into higher-yield retail (credit cards, microfinance), KVB is directly challenging larger private-sector peers on product breadth and asset quality.

Why it matters

For DSAs and loan connectors, KVB's expanded corporate mandate and microfinance co-lending appetite create new sourcing opportunities. A private bank re-committing to corporate lending with renewed risk discipline signals demand for ticket sizes and borrower segments that had contracted. Microfinance and microloans via BCs open distribution channels for sub-retail credit.

For lenders and NBFCs seeking to syndicate or co-lend, KVB's pivot is material: a cleaner balance sheet and stated risk metrics give partners clearer underwriting guardrails. The affordable housing focus—a segment prioritized for priority-sector compliance—also aligns with RBI incentives, making partnership terms predictable.

Sources

Join the conversation on LinkedIn →
Finsamudra DeskNewsroom · 29 May 2026, 4:30 pm IST
See all

Get the Morning Brief

India's lending news before your first call — subscribe free

The same daily intelligence 30,000+ CXOs, DSAs and finance professionals follow on LinkedIn, with the Finsamudra take.

The Morning Brief · Free

Get India's lending news before your first call

The daily intelligence 30,000+ finance professionals follow on LinkedIn, in one short email from the Finsamudra Desk.